The CMR Green Technologies IPO opened on June 3, 2026, and quickly attracted attention from retail and institutional investors alike. This ₹630.88 crore mainboard issue is the first major IPO to break India’s prolonged mainboard subscription dry spell. Before applying, investors need to understand the company’s financials, valuation, and risks in full.
Table of Contents
What Is CMR Green Technologies IPO?
CMR Green Technologies IPO is a ₹630.88 crore mainboard book-built issue comprising entirely an Offer for Sale (OFS) of 3.29 crore equity shares. The company is one of India’s largest non-ferrous metal recyclers, focused on secondary aluminium and zinc alloy production. The IPO opened on June 3, 2026, and closes on June 5, 2026, with listing expected on June 10, 2026 on both BSE and NSE.
CMR Green Technologies Company Overview
Founded in 2006, CMR Green Technologies Limited is headquartered in India and operates as one of the country’s leading non-ferrous metal recycling companies. The company converts aluminium-based metal scrap into high-quality secondary products — primarily aluminium alloys (ingots and in liquid form), zinc alloys, aluminium billets, and furnace-ready metal scrap.
Business Model
CMR Green procures metal scrap from domestic and international sources spanning Asia, Africa, the Middle East, Europe, and the Americas and processes it at 13 strategically located manufacturing facilities across India. Its combined installed capacity is approximately 6,15,150 MTPA, nearly four times the capacity of its nearest domestic competitor.
One of its key differentiators is its ability to deliver molten aluminium at 660°C directly to OEM foundries. This eliminates the re-melting step at the customer’s end, saving time, energy, and cost creating strong structural stickiness.
Products and Services
- Recycled aluminium alloy ingots
- Liquid aluminium alloys (direct to OEM foundries)
- Zinc die-casting alloys
- Aluminium billets (for extrusion applications)
- Furnace-ready scrap of stainless steel, copper, brass, and lead
Key Customers
The company’s major automotive OEM customers include Honda Cars India, Bajaj Auto, Hero MotoCorp, Royal Enfield Motors, and India Yamaha Motor. Repeat clients account for approximately 96% of revenue in 9MFY26. Relationships with its top five customers span 16 to 19+ years.
Industry Position and Market Opportunity
CMR Green holds the highest market share in India’s secondary aluminium industry by revenue in FY25. India currently recycles only around 40% of its recyclable metal waste despite being one of the world’s largest aluminium consumers. This structural gap creates a large addressable opportunity. Government policy support for circular economy practices, rapid industrialisation, and sustainability mandates from global automakers are driving further demand for recycled aluminium.
The company also has strategic equity and technology alliances with Japanese firms, including Toyota Tsusho, Nikkei MC Aluminium, and Nippon Light Metal, which reinforces its access to the Japanese automaker supply chain in India.
CMR Green Technologies IPO Details
| Parameter | Details |
|---|---|
| IPO Opening Date | June 3, 2026 |
| IPO Closing Date | June 5, 2026 |
| Allotment Date | June 8, 2026 |
| Listing Date | June 10, 2026 |
| Price Band | ₹182 – ₹192 per share |
| Face Value | ₹2 per share |
| Lot Size | 78 shares |
| Minimum Investment (Retail) | ₹14,976 (1 lot at upper price band) |
| Maximum Investment (Retail) | ₹1,94,688 (13 lots) |
| Issue Size | ₹630.88 crore |
| Issue Type | Book-built, entirely OFS |
| Total Shares Offered | 3,28,58,323 equity shares |
| Listing Exchange | BSE and NSE |
| Registrar | KFin Technologies Limited |
| Lead Managers | Equirus Capital, ICICI Securities, Motilal Oswal Investment Advisors |
| QIB Quota | 50% |
| NII Quota | 15% |
| Retail Quota | 35% |
| Pre-IPO Market Cap | ~₹4,205.87 crore (at upper band) |
| Anchor Allotment | ₹188.43 crore raised from 18 anchor investors on June 2, 2026 |
Important Note: This IPO is a pure OFS. The company itself will not receive any proceeds from the issue. All funds go directly to the selling shareholders promoter group entities (Mohan Agarwal, Gauri Shankar Agarwal HUF, Mohan Agarwal HUF) and investor shareholder Global Scrap Processors.
CMR Green Technologies IPO GMP Today
Latest GMP: As of June 4, 2026, the grey market premium (GMP) for CMR Green Technologies is approximately ₹63–₹68 per share, implying a potential listing price of around ₹255–₹260 versus the upper issue price of ₹192. This translates to an estimated listing gain of roughly 33–35%.
GMP Trend
| Date | GMP (₹) | Estimated Listing Price (₹) | Premium (%) |
|---|---|---|---|
| May 28, 2026 | ~₹24 | ~₹216 | ~12.5% |
| June 1, 2026 | ~₹45 | ~₹237 | ~23.4% |
| June 3, 2026 | ~₹62–₹63 | ~₹254–₹255 | ~32–33% |
| June 4, 2026 | ~₹63–₹68 | ~₹255–₹260 | ~33–35% |
GMP has moved sharply upward since subscription opened, driven primarily by strong retail and NII demand on Day 1.
What GMP Means And What It Doesn’t
The grey market is an unofficial, unregulated channel where unlisted shares are traded before an IPO lists. GMP figures represent market sentiment, not guaranteed returns. A high GMP today can compress or reverse before listing, especially if broader market conditions change or QIB participation disappoints at the final hour.
Grey Market Risks to Keep in Mind
- No regulatory oversight; transactions carry counterparty risk
- GMP can change overnight based on market mood
- GMP-based listing estimates have missed actual listing prices significantly in the past
- Should be used only as one data point, not the sole reason to apply
CMR Green Technologies IPO Subscription Status
Image 4: CMR Green Technologies IPO Subscription Status — Category-wise subscription data
The IPO was fully subscribed on Day 1 itself, driven by retail and NII investors.
Day 1 Subscription (As of Close, June 3, 2026)
| Category | Subscription |
|---|---|
| Retail Individual Investors (RII) | 2.45x |
| Non-Institutional Investors (NII) | 5.67x |
| Qualified Institutional Buyers (QIB) | 0.03x |
| Overall | 2.45x |
Key Observations
- Retail and NII demand was strong and led Day 1 oversubscription
- QIB participation was minimal on Day 1, which is typical institutions often submit bids on the final day
- The issue was fully subscribed within hours of opening on June 3
- ₹188.43 crore was raised from 18 anchor investors at ₹192/share ahead of the public issue opening
The IPO subscription is live through June 5, 2026. Final subscription figures across all categories will be available after the close of Day 3. Investors can track real-time data on NSE and BSE
CMR Green Technologies Financial Performance
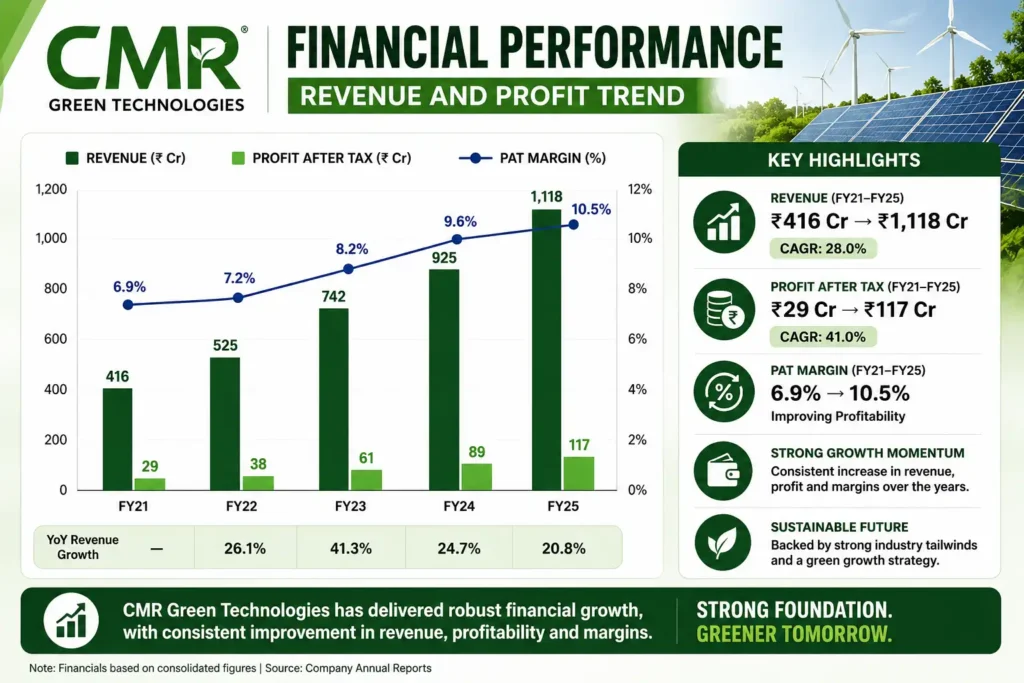
Revenue from Operations
| Year | Revenue (₹ Crore) | YoY Growth |
|---|---|---|
| FY23 | 5,868.51 | — |
| FY24 | 5,952.44 | ~1.4% |
| FY25 | 6,666.48 | ~12.0% |
| 9MFY26 (Apr–Dec 2025) | 6,291.00 | On track for record |
Revenue grew at a CAGR of approximately 7% between FY23 and FY25. In just the first nine months of FY26, revenue crossed ₹6,291 crore, pointing to continued top-line momentum.
Profitability
| Year | PAT (₹ Crore) | PAT Margin |
|---|---|---|
| FY23 | 104.80 | ~1.8% |
| FY24 | -838.56 | (exceptional item) |
| FY25 | 155.04 | ~2.3% |
| 9MFY26 | 162.39 | ~2.6% |
The massive FY24 loss was not an operational failure. It was caused by a one-time ₹1,239.63 crore non-cash goodwill impairment linked to a merger undertaken in FY20. The underlying business remained cash-generative through that period. Profitability recovered strongly in FY25 and continued improving in 9MFY26.
EBITDA
| Year | EBITDA (₹ Crore) | EBITDA Margin |
|---|---|---|
| FY23 | ~207 crore (est.) | ~3.5% |
| FY24 | ~266 crore (est.) | ~4.5% |
| FY25 | ~299 crore | ~4.5% |
| 9MFY26 | 324.44 | ~5.1% |
EBITDA per metric tonne improved from ₹6,908 in FY24 to ₹10,552 in 9MFY26 a significant jump in unit economics.
Debt and Balance Sheet
| Parameter | FY23 | FY24 | FY25 | Dec 2025 |
|---|---|---|---|---|
| Total Borrowings (₹ Crore) | 368 | ~713 | ~942 | 1,303.22 |
| YoY Change | — | ~94% | ~32% | ~38% |
Debt has risen sharply. Since the IPO is entirely an OFS, none of these proceeds will reduce borrowings. This remains a key concern for long-term investors.
Cash Flow
Operating cash flow turned negative in FY25 (-₹92 crore) and worsened to approximately -₹388 crore by December 2025. This was driven by a customer-driven shift to 90-day credit cycles and higher inventory post capacity expansion. While not alarming in isolation, sustained negative operating cash flow needs monitoring.
Return Ratios
| Ratio | Value |
|---|---|
| RoCE (9MFY26 annualised) | ~12% |
| RoE (9MFY26 annualised) | ~12% |
| EPS (FY25) | ₹6.5 per share |
| EPS (9MFY26 annualised) | ~₹8.8–₹10 per share |
CMR Green Technologies Strengths
- Largest domestic player: CMR holds the highest market share in India’s secondary aluminium market by revenue in FY25, with installed capacity nearly four times its nearest rival.
- Direct molten metal advantage: Delivering liquid aluminium directly to OEM foundries eliminates re-melting costs for customers, creating structural switching costs.
- Long-standing customer relationships: Top customers have been with CMR for 16 to 19+ years. Repeat clients accounted for ~96% of revenue in 9MFY26.
- Japanese technology alliances: Partnerships with Toyota Tsusho, Nikkei MC Aluminium, and Nippon Light Metal provide access to advanced casting technology and anchor relationships with Japanese automakers in India.
- Scale advantages: 13 facilities across India allow procurement leverage, logistical efficiency, and capacity for large OEM clients.
- Improving unit economics: EBITDA per MT nearly doubled from FY24 to 9MFY26, reflecting better pricing and operational leverage.
- Domestic sourcing shift: CMR reduced its import dependence significantly, shifting domestic raw material sourcing from 26.85% in FY25 to 97.5% in 9MFY26. This insulates margins from forex and freight risks.
- Green credentials: Recycled aluminium uses up to 95% less energy than primary aluminium production, aligning with ESG mandates from global OEMs and investors.
- Favourable industry tailwinds: India’s 40% metal recycling rate leaves substantial room for sector growth as policy support and EV adoption accelerate scrap availability.
CMR Green Technologies Risks
- Pure OFS structure: The company receives zero proceeds from this IPO. All funds go to existing shareholders exiting their stake. This raises legitimate questions about why insiders are selling rather than retaining shares.
- Rising debt with no relief: Total borrowings reached ₹1,303 crore by December 2025, up 82.9% in FY25 alone. The IPO does nothing to reduce this burden.
- Thin profit margins: Net margins of 2.3–2.6% leave very little cushion. Any adverse movement in scrap prices, aluminium LME rates, or freight costs can compress profits sharply.
- Negative operating cash flows: Sustained negative operating cash flows in FY25 and 9MFY26 signal that working capital management needs improvement, even if partially explained by capacity expansion.
- Customer concentration: Top three customers contributed ~21% of revenue in 9MFY26. Losing even one large OEM relationship would materially affect the business.
- Industry cyclicality: Automotive sector demand directly drives CMR’s volumes. Any slowdown in passenger vehicle or two-wheeler production has an immediate downstream impact.
- EBITDA margin gap versus peers: At 4.5–5.1%, CMR’s EBITDA margins lag Gravita India (~10%), Pondy Oxides (~7%), and Jain Resource (~6%). Superior peers trade at higher valuations with better margins.
- Regulatory and environmental compliance: Metal recycling is subject to evolving environmental regulations, scrap sourcing norms, Extended Producer Responsibility (EPR) mandates, and pollution control requirements.
- FY24 loss concerns: While the ₹838 crore loss was largely a non-cash accounting item, the goodwill impairment highlights integration risks from historical acquisitions.
- Second IPO attempt: This is CMR’s second try at listing. The first attempt in 2021, which received SEBI approval in February 2022, was abandoned. Investors should factor in this earlier hesitation.
Peer Comparison
CMR Green Technologies does not have a direct listed peer at the same revenue scale. However, comparisons can be drawn with other listed non-ferrous metal recyclers.
| Company | Revenue (FY25 approx.) | Net Margin | EBITDA Margin | P/E Range | Market Cap (approx.) |
|---|---|---|---|---|---|
| CMR Green Technologies | ₹6,666 crore | ~2.3% | ~4.5% | ~19–29x | ~₹4,206 crore |
| Gravita India | ₹3,500–₹4,000 crore (est.) | ~5–6% | ~10% | ~30–40x | Higher per margin |
| Pondy Oxides & Chemicals | Smaller scale | Higher | ~7% | ~25–35x | Smaller cap |
| Jain Resource Recycling | Smaller scale | Higher | ~6% | ~25–32x | Smaller cap |
| Baheti Recycling Industries | Smaller scale | Variable | Variable | Variable | Smaller cap |
Key Takeaways from the Comparison
CMR is significantly larger in revenue than its listed peers but trades at lower margins. The listed peer group rules at P/E multiples of 25–76x, with an average of around 52.7x. CMR at ~19–29x P/E appears discounted relative to the group average, but the margin gap justifies some discount.
On P/Sales, CMR trades at a fraction of Gravita India’s multiple, reflecting its lower profitability per rupee of revenue.
CMR Green Technologies IPO Valuation Analysis
P/E Ratio at Issue Price
At the upper price band of ₹192, the P/E ratio based on FY25 EPS of ₹6.5 works out to approximately 29.5x. Ventura Securities calculates it at 27.1x based on annualised 9MFY26 earnings.
Using forward estimates of ~₹10 EPS for FY27, the forward P/E comes to roughly 19x.
Industry Average
Listed metal recycling peers (Gravita India, Jain Resource, Pondy Oxides) trade at P/E multiples of 25–76x, with an average around 52.7x. On that basis, CMR appears undervalued.
However, this comparison needs qualification. CMR’s net margins (2.3–2.6%) are substantially lower than those peers. A lower-margin business typically deserves a lower earnings multiple.
EV/EBITDA
Enterprise Value stands at approximately ₹5,500 crore at issue price. Based on 9MFY26 EBITDA annualised, EV/EBITDA is around 12.5x — reasonable for a capital-light recycling business with large scale.
Fair Valuation Assessment
At ₹192 per share:
- The issue is not cheap given thin margins and rising debt.
- However, given the sector tailwinds, industry leadership, improving EBITDA per MT, and a forward P/E of ~19x, the IPO does not appear aggressively overpriced either.
- The market has broadly agreed the GMP of ~₹63–68 suggests the street expects a listing premium.
The biggest valuation concern is whether margin improvement is sustainable. If EBITDA margins move toward 6–7% over the next 2–3 years with volume growth, the current price will look attractive in hindsight. If margins stagnate at 4.5%, the re-rating case is weaker.
Should You Apply for CMR Green Technologies IPO?
Reasons to Apply
- Market leader in a structurally growing industry with low current recycling penetration
- EBITDA per MT improving rapidly; unit economics moving in the right direction
- Japanese technology alliances add credibility and anchor customer stability
- Valued at a discount to most listed peers on headline P/E
- Strong Day 1 subscription suggests healthy demand; GMP signals listing upside
- Improving PAT margins (2.3% in FY25, 2.6% in 9MFY26)
Reasons to Avoid
- Pure OFS no funds going to the company; promoters and investors are exiting
- Debt has surged to ₹1,303 crore with no reduction planned
- Negative operating cash flows for two straight periods
- Thin EBITDA margins well below comparable listed peers
- This is the company’s second IPO attempt; the first was abandoned
- QIBs showed minimal enthusiasm on Day 1 (0.03x)
For Short-Term / Listing Gain Investors
The GMP of ~₹63–68 suggests a possible listing in the ₹255–₹260 range, implying a 33–35% premium over the issue price. If market conditions hold and QIBs participate actively on the final day, a strong listing is plausible. That said, GMP-based predictions carry significant risk. Apply at the upper band only and avoid assuming guaranteed listing gains.
For Long-Term Investors
The long-term thesis depends on two things: margin expansion and debt reduction. If CMR can push EBITDA margins toward 6–7% and demonstrate disciplined cash flow management over the next two to three years, it becomes an interesting hold. Current metrics alone — thin margins, negative cash flows, and rising debt do not support an aggressive long-term buy thesis at this price. Investors with a three-to-five-year horizon can consider a moderate allocation and monitor post-listing quarterly results.
Listing Gain Potential
Positive Scenario
QIBs participate strongly on the last day, pushing total subscription well above 10x. Market conditions stay stable. Listing at ₹255–₹265, delivering a 33–38% return on the issue price.
Neutral Scenario
Moderate overall subscription (3–6x). Market remains flat. Listing at ₹210–₹230, a 10–20% premium over issue price.
Negative Scenario
Broader market corrects before June 10. QIBs remain muted. GMP compresses. Listing at or below ₹192. In extreme cases, listing below issue price is possible, especially for a pure OFS with no fresh capital deployment story.
Expert Verdict
Brokerage ratings on CMR Green Technologies IPO lean cautiously positive.
Ventura Securities assigned a Subscribe rating, citing market leadership, growing technological capabilities, and a P/E of 27.1x on FY25 annualised earnings.
SP Tulsian rated it Very Average, pointing to EBITDA margins below peers, a P/E of ~19x on FY27 estimates (which looks fair but not cheap), and the OFS-only nature of the issue.
Arihant Plus noted that the P/E of ~29.5x at the upper band is below the peer average of 52.7x, suggesting room for re-rating if margins improve.
Our Assessment
CMR Green Technologies is a real business India’s largest non-ferrous metal recycler with a clear market position and improving economics. The GMP and Day 1 subscription suggest positive market sentiment in the short run.
However, the OFS structure, rising debt, negative operating cash flows, and margins significantly below listed peers present genuine concerns that long-term investors cannot ignore. The IPO appears fairly priced for listing gains and offers moderate value for patient long-term investors who believe in the sector’s structural growth story.
Conservative approach: Apply for listing gains, but do not chase the stock at significant premiums post-listing if the financials do not improve materially within two quarters.
Also Read
- Tata Group Dividend: Best Tata Stocks for Dividend Income in 2026
- LPG Price Hike June 2026: 5 Indian Energy Stocks That Could Benefit
- HDFC Bank Share Price Target 2026 to 2030: Can It Cross ₹3,500? Expert Forecasts Inside
- Hexagon Nutrition IPO 2026: GMP Today, Price Band, Allotment Date & Should You Apply?
Frequently Asked Questions (FAQs)
1. What is CMR Green Technologies IPO?
Ans:- CMR Green Technologies IPO is a ₹630.88 crore mainboard book-built issue comprising entirely an OFS of 3.29 crore equity shares. The company is India’s largest non-ferrous metal recycler by revenue and capacity.
2. What is the CMR Green Technologies IPO price band?
Ans:- The price band is fixed at ₹182 to ₹192 per equity share.
3. What is the lot size?
Ans:- The minimum lot size is 78 shares. Retail investors need at least ₹14,976 to apply for one lot at the upper price band.
4. What is the GMP today?
Ans:- As of June 4, 2026, the grey market premium is approximately ₹63–₹68 per share, implying a potential listing price of ₹255–₹260 and a 33–35% premium over the issue price.
5. What is the subscription status?
Ans:- As of the end of Day 1, the IPO was subscribed 2.45x overall. Retail was at 2.45x, NII at 5.67x, and QIBs at 0.03x.
6. Is the IPO good for listing gains? Based on the GMP, listing gains of 30–35% appear likely if market conditions hold and QIBs participate on Day 3. However, GMP is not a guarantee and actual listing price can differ significantly.
7. Is the IPO good for long-term investment?
Ans:- A moderate allocation may work for long-term investors who believe in India’s metal recycling growth story. However, rising debt and thin margins are concerns. Margin improvement and cash flow recovery post-listing should be monitored closely before adding more.
8. When is the allotment date?
Ans:- The basis of allotment is expected to be finalised on June 8, 2026. Shares should be credited to demat accounts by June 9, 2026.
9. When is the listing date?
Ans:- CMR Green Technologies shares are scheduled to list on BSE and NSE on June 10, 2026.
10. Should retail investors apply for this IPO?
Ans:- Retail investors comfortable with the OFS risk and looking for short-term listing gains may apply for one to two lots. Long-term investors should review post-listing quarterly results before building a larger position. Never invest more than you can afford to stay locked in.
11. Why is this IPO entirely an OFS?
Ans:- The entire issue is an Offer for Sale, meaning promoters and existing investors — including Global Scrap Processors, Mohan Agarwal, and associated entities — are exiting their holdings. The company itself receives no proceeds from the IPO.
12. Who is the registrar for this IPO?
Ans:- KFin Technologies Limited is the registrar to the CMR Green Technologies IPO.
Useful Links
- SEBI — Official Regulator — For regulatory disclosures and IPO guidelines
- NSE India — Live subscription status and bidding data
- BSE India — Allotment status and IPO documents
- CMR Green Technologies RHP on SEBI — Red Herring Prospectus for detailed financial and legal disclosures
- KFin Technologies — Registrar — For allotment status lookup using PAN/Application number
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Investments in securities are subject to market risks. Please read all IPO-related documents carefully before investing. Consult a SEBI-registered financial advisor if needed.